Article label: Opinion
The useful question for leadership teams right now isn’t “what does the law require this year?” It’s “what capability do we need to hold regardless of what the law requires?”
The useful question for leadership teams right now isn’t “what does the law require this year?” It’s “what capability do we need to hold regardless of what the law requires?”
The center of gravity for climate leadership is shifting, with China making landmark pledges and significant progress emerging from Africa, South Asia, and Eastern Europe.
The FCA says its approach to what listed companies will be expected to report in the future is pragmatic and proportionate.

The EC is aiming to adopt this delegated act in late 2026, applying to in-scope entities in respect of financial year 2027.
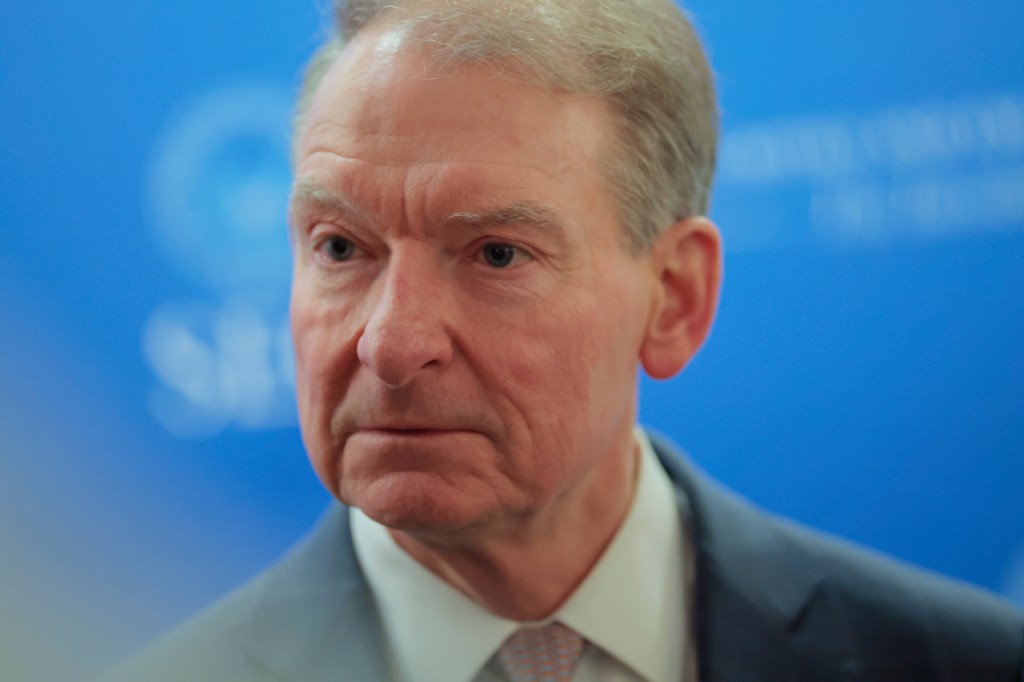
Paul Atkins has threatened to ban overseas companies from using IFRS if they include any sustainability concerns.
A closer reading of the Chair’s comments in the speech shows, as a primary focus, explicit and very prosaic concerns about the IFRS Foundation’s long-term solvency and stability.
The FCA has outlined its next steps, which focus on enhancing and simplifying the sustainability reporting framework.
If endorsed, the use of these standards in reporting would initially be voluntary, but may become mandatory.