Late 2026 sees compliance and legal professionals in the financial services sector gearing up for a highly fluid landscape featuring proposed regulations out for comment, eagerly awaited pending legislation in Congress, and possibly a new composition to the Congressional body politic itself.
They must balance all of this with invigorated state attorneys general and the expectations of stakeholders seeking clarity on the business’s perspective on how they might effectuate these pending and (mostly) more streamlined rules, if passed, going forward.
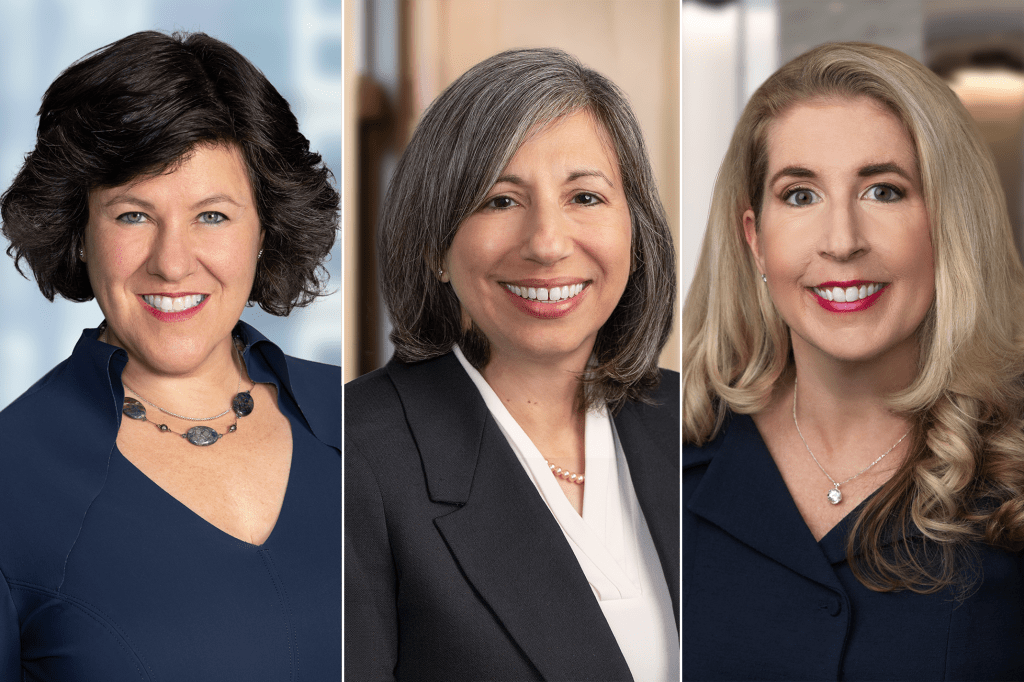
I spoke with three attorneys from Morgan Lewis about what they foresee and what they are hearing from and telling their clients in this time of flux.
Carolyn Welshhans is a partner at the firm who previously served as the associate director of the SEC’s Division of Enforcement. Alice Hrdy is a partner at the firm who previously served as the principal deputy in the Consumer Financial Protection Bureau’s (CFPB’s) Office of Supervision Policy and assistant director of the Federal Trade Commission’s Bureau of Consumer Protection, Division of Financial Practices. And Stacie Hartman is a partner at the firm leading cases before US courts and in enforcement proceedings before the Commodity Futures Trading Commission (CFTC) and other federal financial agencies.
The Clarity Act
The Digital Asset Market Clarity Act or “Clarity Act” is a proposed US legislative bill designed to create a comprehensive regulatory framework for cryptocurrencies and digital assets. The US Senate failed to invoke cloture on the legislation on September 15, falling short of the 60 votes needed to advance the procedural motion.
What happened?
The effort for a revised Clarity Act was a bit of a Hail Mary, Hartman said. The fact that a few Republicans voted against it suggests that, while the ethics issue loomed large, the other issues also played a role, she added.
“The CFTC (and SEC) have been gearing up to act ever since the legislation was in jeopardy. Chairman Selig has been talking about what the CFTC can do in the absence of a Clarity Act, and that’s been a refrain over the past two years: Rely as much as possible on the existing regulatory framework.
“The agencies will have their work cut out for them, but they made headway with their taxonomy guidance in March to demarcate jurisdiction. Legislation is needed for reliably enduring clarity, but industry hasn’t halted progress in its absence,” Hartman said.
Questions about yield and ethics had dogged the bill for some time, with the ethics provision serving to kill cloture.
Senate Republicans had recently introduced last-minute revisions to try to garner enough support to break a filibuster. But Senate Democrats remained opposed to any ethics provision that gave the Department of Justice the power to bring enforcement actions against the President.
As to the yield issue, Hartman explained, this has been centered on a hard-fought legislative compromise that bans digital asset rewards functionally equivalent to bank deposit interest while permitting narrow incentives tied to active platform utility.
The crypto industry has sought to preserve their ability to issue something like a yield or reward of their own for crypto deposits, arguing strict bans hurt innovation, among other things.
Hartman identified another aspect of the bill that was debated this year: The passage of related legislation called the BRCA or Blockchain Regulatory Certainty Act. This legislation establishes a safe harbor ensuring that blockchain developers, software publishers, and infrastructure providers who do not hold or custody consumer funds are not classified as “money transmitters.”
“The BRCA would protect software developers and miners and validators from being classified as money transmitters who do not control or custody customer funds. The financial markets have had vendors largely outside the scope of regulation. But when registered entities have relied on those vendors to satisfy some of their own regulatory requirements, that has sometimes brought them within the reach of the CFTC or SEC,” she said.
If there was yet a fourth contentious aspect to the bill, it was the concept of vertical integration, with the debate regarding whether crypto firms should combine multiple financial functions, such as serving as exchanges, brokerages, and trading firms, under one roof. That type of integration reminds people of the risks that led to FTX’s collapse and is a conflict-of-interest concern.
Welshhans added her thoughts about the Clarity Act, noting the timing aspect. “It will be interesting to see how quickly they can resolve these roadblocks, how strong the push is to do so,” she said.
Hartman pointed out that the financial service regulators are not really waiting around for Congress when it comes to creating a digital asset framework.
“They have been taking actions such as issuing guidance and no-action relief and many notices of proposed rulemaking in this arena, particularly as it relates to digital assets in the US.”
Welshhans agreed, saying “the SEC’s proposed regulatory framework aligns with the Trump Administration’s priorities in terms of offering safe harbors and flexibility, so there is likely a fair amount of coordination going on behind the scenes.”
She and Hartman said that while the agencies issue these guidance documents and proposed rulemaking, they are not getting too far ahead of where legislation could ultimately land, because then they would have to revise their regulations. But they have started to delineate which agency has responsibility over what, explaining taxonomy among other things.
Collaboration
The discussion about the SEC and CFTC working closely with each other to lay the groundwork for a federal digital asset regulatory framework prompted a discussion around the degree of coordination between the two agencies.
“We’ve never seen that level of collaboration before,” Hartman said.
Merging the agencies may be more a topic at cocktail parties for people who care about this stuff, Hartman said. ‘Will there be a merger between these two agencies?’” is the query posed, she said. “Likely no, given their different congressional oversight, but there is a strong and mutual desire to get things done and be very forward-leaning, and it’s well beyond the kind of collaboration I’ve seen in 30 years of observing these two agencies function.”
Banking and fair access
The US House of Representatives passed the Main Street Capital Access Act, saying it would reduce regulatory burdens on community banks and expand local credit. Hrdy sees whether it can make it through the Senate as an open question.
As for regulatory issues, the bank agencies in general have been focused on finalizing their respective rules, including regarding unsafe and unsound banking and on defining it for the first time, she observed. “And then they raised the threshold of what bank examiners can identify as a ‘matter requiring attention,’” she added.
What this signals to banks, she said, is that although examiners have been seen as powerful and having discretion to identify deficient practices, these new initiatives “demonstrate the agencies’ recognition of the need for clearer standards to enable the banks to have an ability to better understand the agencies’ approach and be proactive in managing their risks in light of articulated standards, as opposed to intervention by the agencies.”
Hrdy mentioned that 39 state banking associations just announced their intention to establish their own blockchain network, called BankChain Alliance.
“It will help them come together as a consortium of state-chartered banks and try to compete with crypto-native companies and the larger banks when it comes to digital assets. It’s a significant signal of collective action on the part of smaller banks,” she said.
The CFPB’s fate
I asked Hrdy about the consumer-focused and Dodd-Frank-Act-borne agency where she used to work. Is it still on the potential chopping block and will it be able to exercise enough independence to function according to its mandate?
“The Senate Banking Committee is acting on the nomination of a permanent director which is a good sign in terms of achieving steady leadership at the CFPB. The CFPB Reform Act draft has been introduced by House Financial Services Committee Republicans to restructure and limit the powers of the agency, but it is not an initiative to eliminate the agency. Instead, it’s more designed to restructure its funding and how many banks and financial services companies are subject to it,” Hrdy said.
Hrdy did not dismiss those provisions, though, as putting the agency under the appropriations process would be a key point of debate for many in Congress.
Hrdy said the proposal to reduce the number of employees there has been put on hold by joint motion of the CFPB and the employee union, pending confirmation of a permanent director. And she said the agency’s open banking rule, which is known as the Personal Financial Data Rights or Section 1033 rule, is currently paused and undergoing major revision.
“The real question for reform is whether there is a path forward in terms of bipartisan support for curtailing some of its authority, mainly in supervision and enforcement,” Hrdy said. “If confirmed, a new permanent director will likely be consulted on the parameters of the Reform bill.”
The SEC’s rulemaking ambitions
The SEC has embarked on an incredibly ambitious list of proposed rulemaking, including pay-to-play reform, executive compensation disclosure, easing the burdens of recordkeeping, plus ongoing initiatives under the banner of “Making IPOs Great Again,” for example.
What is Welshhans waiting to see from the SEC in terms of its RegFlex agenda?
“It came out later than usual, but it’s certainly touching on multiple areas of the market. The proposal around the custody rules is one we’re focused on and the proposal around the amendments to the trade-through rule,” she said. The latter amendments would rescind the order protection rule, which generally requires trading centers to satisfy better-priced quotations on other venues.”
“And it’ll be interesting to see the breakdown of the comments received, especially for the move from quarterly annual reporting to semi-annual, as what we have heard is that the comments lean heavily on the side of not moving to semi-annual reporting. In general, comments often raise economic considerations and the commissioners take those seriously, with their Division of Economic and Risk Analysis focused specifically on it,” Welshhans said.
Welshhans pointed out that we can’t forget that the SEC lost about 15% to 20% of its staff because it took the buyout.
“That has implications for rulemaking, because it’s a heavy lift. Most of the rulemakings get spread across different divisions in terms of the work needed and weighing in on them, so even if one division takes the lead, others are often involved. It’s hard to see how this level of activity can be sustained with the staff levels as they are right now,” she added.
I asked Welshhans about the impact of some of these proposed rules on her clients and their compliance programs and whether they were eagerly awaiting certain ones.
She said they are sitting back and waiting on the semi-annual reporting proposal, with their decisions on that one having a lot to do with what their peers end up doing (more frequent filings than what the final rule ends up allowing for or not) and what investor constituencies are seeking.
“And much of that will be gleaned from discussions and examinations of earnings releases and things of that nature. So, the rule proposal on semi-annual reporting and, if you’re a trader or an exchange, the trade-through proposal are both of great interest.”
And speaking more generally, Welshhans said: “We can’t forget that we are seeing a lot of change from one administration to another here, to a degree that is atypically high, and a midterm election coming, both of which present challenges for businesses trying to plan for the long-term. Compliance and legal teams would like to see some consistency and some predictability soon,” she added.
In terms of a business’s compliance program, she advises building from the strong compliance program they have and considering the pivots they would need to make, so there is a plan of action there, if needed.
Hartman agreed, saying that the perceived lower-enforcement posture by the CFTC does not guarantee having a lighter touch with a registered firm’s compliance. It’s not the time to slash resources or staffing or undo things. Businesses seek certainty, not whiplash, and she added that the statute of limitations applicable here is longer than any one administration.
Hrdy pointed out that since some regulations have been pared back at the SEC, and court rulings even in the Biden administration rules against the agency, her clients have had time to think about how to approach a less active environment. “They are evaluating their compliance programs and systems now that they don’t have to be so reactive in posture,” she said.
“They are pressure-testing it. And certainly in the area of the Bank Secrecy Act and money laundering, that has not at all let up, so that is an area where the firms are continuing to dedicate substantial resources.”
Hrdy pointed out that the state attorneys general and state baking regulators “have not put down their pencils. They are still very active, so it’s a question of being compliance-smart, with your resource allocation, with your approach. There will still be changes to come in terms of consumer-focused regulation from other aspects of the government, but the executive branch of it will stay pretty much at the same level. This gives supervised institutions the opportunity to evaluate what works best for compliance and which systems are best working to support the program.”
Bustling SROs and prediction markets
Hartman pointed out that the self-regulatory organizations (SROs), such as FINRA, the National Futures Association, and exchanges themselves, have remained quite active.
“There’s been a bit of an increase, even, in some SRO enforcement action. And the prediction markets have taken up a lot of space in the compliance conversation, with the main question being, of course, does the Commodity Exchange Act preempt state law? Are these swaps, which remain in the CFTC’s exclusive jurisdiction, or not swaps and potentially subject to state gambling laws?” Hartman added.
She said the count is now up to 20 states that are in litigation with the prediction markets, in many of them with the CFTC as well, which is another first. The CFTC is making itself a plaintiff to sue the states over the CFTC’s exclusive jurisdiction, and it’s not anything we have ever seen before,” she added.
“To make matters more interesting, there’s been conflicting judicial decisions across jurisdictions in this arena. And even a split among appellate courts, with the Ninth Circuit’s ruling that sports event contracts are sports bets that should be state-regulated in a Nevada case, and the Third Circuit decision saying that they are federally regulated swaps, and thus that New Jersey cannot regulate them.”
Hartman thinks more states and even cities (one has weighed in already) will join the fray.
“And state AGs will continue to bring cases, or their securities regulators will, but there has also been an increasing trend of states enacting anti-prediction market legislation, whether that’s in the form of taxation or licensing requirements,” she added.
Hartman also said the compliance challenge for businesses is in the insider trading area, where even non-financial firms are discovering they must tailor their insider-trading prohibitions in their codes of conduct or employee handbook with this surge in the prediction markets and their varied offerings.
“This is something we are increasingly talking to clients about, as it’s on their mind.”